Investing
Long-Term Investing vs Short-Term Trading
A few years ago, I had four monitors set up on my desk, constantly flashing red and green. I was...
• 8 minutes read
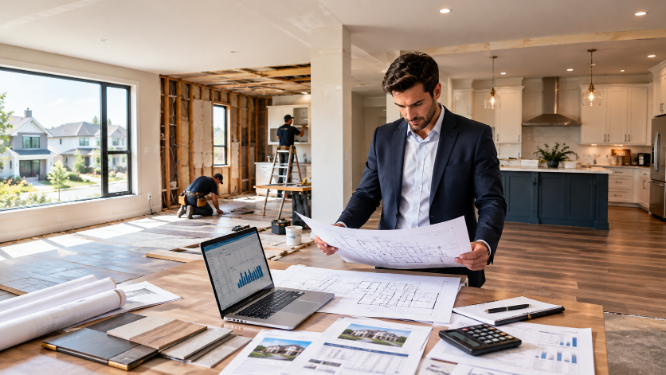
Fix-and-flip real estate investing is a popular strategy for people who want to buy properties, improve their condition, and sell them for a potential profit. Instead of holding a property for many years, investors focus on completing renovations and reselling the property within a planned period. However, purchasing a property and paying for renovations can require a significant amount of money.
This is where fix-and-flip real estate loans can help. These loans are designed to provide financing for certain property investment projects, including the purchase of properties that need repairs and the cost of making improvements. Depending on the lender and loan agreement, the funds may cover the purchase price, renovation expenses, or both.
Although this type of financing can help investors move forward with a project, it also comes with costs and risks. Interest payments, renovation delays, unexpected repairs, and changes in property prices can all affect the final result.
Understanding how fix-and-flip loans work can help investors compare financing options, prepare realistic budgets, and make better decisions before purchasing a property.
In this guide, we will explain what fix-and-flip loans are, how they work, the different financing options available, how lenders evaluate applications, and what investors should consider when planning a renovation and resale project.
Fix-and-flip real estate loans are financing options used by property investors who intend to purchase a property, renovate it, and sell it after improvements are complete.
The term “fix-and-flip” describes the basic investment process. An investor buys a property that needs repairs or improvements, completes the planned work, and puts the property back on the market.
For example, an investor might purchase an older house with an outdated kitchen, damaged flooring, and worn-out fixtures. After buying the house, the investor renovates the necessary areas and prepares it for resale.
If the property sells for more than the total project cost, the investor may earn a profit. However, a higher resale price does not automatically guarantee a successful investment because financing, renovation, holding, and selling expenses must also be considered.
Fix-and-flip loans can be useful when an investor does not want to use all their personal savings for a property purchase. They may also help investors manage the timing of purchase and renovation expenses.
These loans are not suitable for every situation. Their costs, repayment periods, eligibility requirements, and permitted uses vary between lenders and locations.
The process generally begins when an investor identifies a property that could become more valuable after renovation.
Before making an offer, the investor estimates the purchase price, repair costs, expected resale value, and time needed to complete the project. The investor then explores financing options and determines whether the numbers support the investment.
A typical fix-and-flip loan process involves several steps.
The first step is identifying a property that fits the investor's budget and investment strategy.
Investors often look for homes or buildings that need cosmetic improvements, repairs, or other upgrades. However, a low purchase price alone does not make a property a good investment.
The investor should examine the property's location, condition, comparable sale prices, buyer demand, and any legal or structural concerns.
A professional inspection can help identify problems that may not be visible during an ordinary viewing.
After selecting a potential property, the investor prepares a renovation budget.
This budget may include labor, materials, permits, inspections, contractor fees, and other project expenses. It should also include a reserve for unexpected repairs.
For example, replacing kitchen cabinets and repainting walls may be relatively straightforward. Repairing a damaged foundation or replacing an outdated electrical system could be much more expensive.
Accurate estimates are important because renovation costs directly affect the amount of money needed and the potential profit.
The investor compares lenders and submits an application for a suitable loan.
Depending on the lender, the application may require financial information, details about the property, a renovation budget, a proposed project timeline, and information about the investor's experience.
The lender may evaluate the property's current value, expected value after renovations, the amount requested, and the investor's ability to repay the loan.
Some lenders may also require a personal credit check, proof of available funds, or a down payment.
Once the loan is approved and the transaction closes, the investor can begin the project according to the financing agreement.
Some loans provide funds for the property purchase and release renovation money in stages. In these arrangements, the lender may require inspections or evidence that specific work has been completed before releasing additional funds.
Other financing arrangements may cover only the purchase, leaving the investor responsible for paying renovation costs separately.
Understanding how funds are released is essential. A project can face delays if contractors need payments before the lender releases the next portion of the renovation budget.
After renovations are complete, the investor prepares the property for sale.
The property may need professional photography, cleaning, staging, marketing, and a suitable asking price. Once a sale closes, the investor generally uses the proceeds to repay the outstanding loan and applicable fees.
Any amount remaining after all project costs and taxes may represent the investor's profit.
However, if the property sells for less than expected or takes longer to sell, the investor may earn less than planned or lose money.
Investors can explore several financing options for renovation and resale projects. Each option has different requirements, costs, and risks.
Hard money loans are commonly associated with real estate investors who need financing for properties that may not qualify easily for conventional mortgages.
These loans are often secured by real estate, and lenders may place significant emphasis on the property's value and the project's financial potential. However, lender requirements vary.
Hard money loans may offer a relatively fast approval process in some circumstances, which can help investors compete for properties when timing matters.
The main disadvantage is cost. Interest rates and fees can be higher than those associated with some traditional mortgage products. Repayment periods may also be relatively short.
Investors should carefully review the interest rate, origination fees, payment schedule, extension charges, and consequences of failing to repay on time.
Private money loans come from individuals or private investment groups rather than traditional banks.
A private lender may provide funds to an investor in exchange for interest payments, agreed repayment terms, and potentially other contractual protections.
These arrangements can sometimes be more flexible than conventional lending, depending on the parties involved. For example, an investor with a strong project plan may find a private lender who understands the renovation strategy.
However, private financing still requires careful documentation.
The parties should agree on the loan amount, interest rate, repayment date, collateral if applicable, and what happens if the property sells late or the project experiences financial problems.
Both parties should obtain appropriate legal advice before signing an agreement.
Some specialized lenders offer financing that combines the property purchase with a renovation budget.
The lender may calculate the loan using the purchase price, renovation plan, and estimated value after improvements. Funding arrangements differ, and the full renovation budget may not be available immediately.
In some cases, the investor must pay contractors first and then request reimbursement after inspections. In other cases, funds may be released according to an approved draw schedule.
Investors should confirm the exact process before committing to the project.
A renovation loan can help organize project financing, but it does not eliminate the need for personal funds. The investor may still need a down payment, closing costs, reserves, or money to cover expenses that the lender does not finance.
A business line of credit allows an eligible borrower to access funds up to an approved limit.
Depending on the agreement, an investor may use the credit line to cover certain renovation expenses, material purchases, or temporary cash-flow needs.
Unlike a single loan paid out at closing, a line of credit may allow the borrower to draw funds as needed and pay interest according to the amount borrowed and the applicable terms.
However, rates can change, fees may apply, and lenders can impose restrictions on how the money is used.
Investors should make sure the repayment requirements fit the expected project timeline.
Not every fix-and-flip project requires a specialized loan.
Some investors use personal savings, while others work with partners who contribute capital in exchange for a share of the project's results.
Using personal funds may reduce borrowing costs, but it can also tie up money that might be needed for emergencies or other investments.
Partnerships allow investors to combine money, skills, and experience. However, a written agreement should define each person's contribution, responsibilities, decision-making authority, and share of profits or losses.
A partnership does not remove investment risk. Both parties should understand what could happen if the project exceeds its budget or the property fails to sell.
The amount an investor can borrow depends on several factors, including the lender's policies, the property's condition, the purchase price, the renovation budget, the investor's financial position, and the expected value after improvements.
Some lenders consider the property's after-repair value, often called ARV. This is an estimate of what the property may be worth after the planned renovation is completed.
However, ARV is not a guaranteed selling price. The actual sale price may be lower because of market conditions, property defects, buyer negotiations, or changes in demand.
Lenders may also consider the loan-to-cost ratio, which compares the loan amount with eligible project costs, and the loan-to-value ratio, which compares the loan amount with a property's value.
These measures help lenders evaluate risk, but each lender may use different calculations and eligibility standards.
Investors should avoid borrowing the maximum amount simply because it is available. The right loan is one that supports the project while leaving enough financial room to manage unexpected costs and delays.
Some property investors use the 70% rule as an initial screening tool when evaluating potential fix-and-flip opportunities.
Under this rule, an investor aims to pay no more than 70% of a property's estimated after-repair value, minus the estimated renovation cost.
The formula is:
Maximum purchase price = (After-repair value × 70%) − Renovation cost
For example, suppose a renovated property may sell for $250,000 and the estimated renovation cost is $35,000.
The calculation would be:
Estimated after-repair value: $250,000
70% of after-repair value: $175,000
Estimated renovation cost: $35,000
Indicative maximum purchase price: $140,000
This means the 70% rule would suggest a purchase price of approximately $140,000 or less.
However, this is only a rough screening method, not a universal investment rule or a guarantee of profit. The percentage may not suit every market, property type, or financing arrangement.
The investor must still calculate closing costs, interest, insurance, taxes, utilities, selling fees, and other expenses. A property that passes the 70% rule can still produce a loss if the estimates are inaccurate.
Before applying for a loan, investors should prepare a detailed project budget.
The total cost usually includes more than the purchase price and renovation expenses.
Important costs may include:
Property purchase price
Down payment and closing costs
Legal and inspection fees
Renovation materials and labor
Permits and professional services
Loan interest and financing fees
Property insurance and taxes
Utilities and maintenance
Marketing and estate agent fees
Final selling and closing costs
Unexpected repairs and delays
Applicable taxes on investment profits
Consider the following example.
An investor purchases a property for $160,000 and plans to renovate it before resale.
| Project expense | Estimated cost |
|---|---|
| Property purchase | $160,000 |
| Renovation and materials | $30,000 |
| Purchase and legal costs | $5,000 |
| Financing and holding costs | $7,000 |
| Marketing and selling expenses | $10,000 |
| Additional repair allowance used | $3,000 |
| Total project cost | $215,000 |
If the property sells for $245,000, the estimated amount remaining after the listed expenses is $30,000.
This figure is an illustrative pre-tax result, assuming all relevant expenses are included. It is not a guaranteed return.
If the property sells for $225,000 instead, the amount remaining would fall to $10,000. Additional costs or tax liabilities could reduce the result further.
This example demonstrates why investors should estimate the full project cost and test different sale prices before purchasing a property.
Lenders evaluate applications differently, but several factors commonly influence their decisions.
Some lenders review the applicant's credit history, existing debts, income, and available cash.
A strong financial position may improve the investor's financing options, but it does not guarantee approval.
The lender may assess the property's current condition, location, market demand, and expected value after renovation.
Properties in areas with weak demand or uncertain resale values may be harder to finance.
A detailed renovation budget helps show how the investor plans to use the money.
Lenders may ask for contractor estimates, a list of planned repairs, permits, or supporting documents.
Some lenders prefer borrowers who have previously completed renovation projects. Others may consider newer investors, but they might require a larger down payment, additional reserves, or stronger financial documentation.
Beginners should check eligibility requirements before spending money on applications or property inspections.
Lenders may want to understand how the investor plans to repay the loan.
Selling the renovated property is a common exit strategy, but the investor should also consider what happens if the sale is delayed. Any backup option, such as refinancing or renting the property, must be realistic and supported by suitable financing and market conditions.
Fix-and-flip loans are often designed for shorter periods than traditional mortgages, but the exact term depends on the lender and the loan product.
The project may involve several stages: purchasing the property, completing repairs, marketing the property, negotiating with buyers, and closing the sale.
Even a well-planned project can experience delays. Contractors may become unavailable, materials may arrive late, inspections may reveal additional work, or buyers may withdraw from a transaction.
If the loan term ends before the property sells, the investor may need to repay the outstanding balance, qualify for an extension, or arrange another financing solution.
Extensions are not guaranteed and may involve additional fees or different terms.
Before borrowing, investors should compare the expected project duration with the loan term and include enough flexibility to handle reasonable delays.
Financing can help investors purchase and improve properties, but mistakes can quickly reduce the potential return.
Unexpected problems can increase project costs. Investors should inspect properties carefully, obtain realistic estimates, and reserve money for unforeseen repairs.
A project may appear profitable before financing expenses are included.
Investors should calculate the total borrowing cost over the expected loan period and consider what happens if repayment takes longer.
A renovated property may not sell for the price an investor expects.
Research recent comparable sales, account for competing listings, and use conservative estimates rather than relying on the highest asking prices in the neighborhood.
Poor scheduling can delay contractors, inspections, and the final sale.
Create a practical timeline, agree on responsibilities with contractors, and review progress regularly.
Selling the property may be the preferred plan, but market conditions can change.
Investors should assess whether other options are feasible before purchasing. Renting or refinancing may require different property conditions, financing qualifications, and financial calculations.
A short-term loan still needs to be repaid even if the project does not perform as expected.
Investors should understand the repayment date, potential penalties, and their obligations if the property remains unsold.
Comparing loan offers can help investors understand the true cost of financing.
First, compare the interest rate and all associated fees. A loan with a lower advertised rate may still be expensive if it includes substantial origination, valuation, or other charges.
Second, review how the renovation funds are released. If money is paid in stages, confirm the documentation and inspection requirements for each payment.
Third, check the repayment term and whether an extension is possible. Do not assume that the lender will automatically approve extra time.
Fourth, understand the collateral and default provisions. A property-secured loan can put the property at risk if the borrower fails to meet the agreement.
Finally, confirm that the loan suits the project. Consider the purchase price, renovation budget, expected sale price, and likely completion date together.
For significant investments, qualified legal, tax, and financial professionals can help review the financing terms and the project's risks.
Fix-and-flip loans can be useful for beginners who have a realistic project plan, understand the local property market, and can manage the financial obligations involved.
However, beginners should not assume that borrowing money makes a project profitable. Financing increases the amount of money available, but it also creates repayment obligations and additional costs.
A smaller renovation with clearly defined repairs may be easier to manage than a property requiring extensive structural work. Even so, every property should be inspected and evaluated carefully.
New investors should learn how to calculate total project costs, compare recent property sales, estimate renovation expenses, and assess the risks of delayed resale.
It is also important to keep enough money available for unexpected expenses instead of committing every available dollar to the purchase.
If the numbers only work under the most optimistic assumptions, the project may be too risky.
Fix-and-flip real estate loans can help property investors finance purchases and renovations before reselling improved properties. Depending on the lender, available options may include hard money loans, private money financing, renovation loans, business credit lines, or other arrangements.
Each option has different costs, repayment requirements, and eligibility conditions. Investors should compare the complete financing terms instead of focusing only on how quickly they can obtain funds.
A successful project also requires a realistic purchase price, an accurate renovation budget, a practical timeline, and a clear exit strategy.
Before starting a fix-and-flip project, calculate the total investment, estimate several possible resale prices, and prepare for unexpected expenses. Understand the loan agreement and determine how the outstanding balance will be repaid if the property takes longer to sell.
Real estate investing involves risk, and profits are never guaranteed. Careful research, conservative financial estimates, and professional advice can help investors make better-informed decisions when financing property renovations and resales.
A few years ago, I had four monitors set up on my desk, constantly flashing red and green. I was...
• 8 minutes read
Years ago, I used to think the stock market was a playground reserved exclusively for guys in tailored suits who...
• 6 minutes read
Value-Add Real Estate Investing: How Property Improvements Create Potential Returns Real estate investing is not always about buying a property...
• 16 minutes read