Investing
Long-Term Investing vs Short-Term Trading
A few years ago, I had four monitors set up on my desk, constantly flashing red and green. I was...
• 8 minutes read
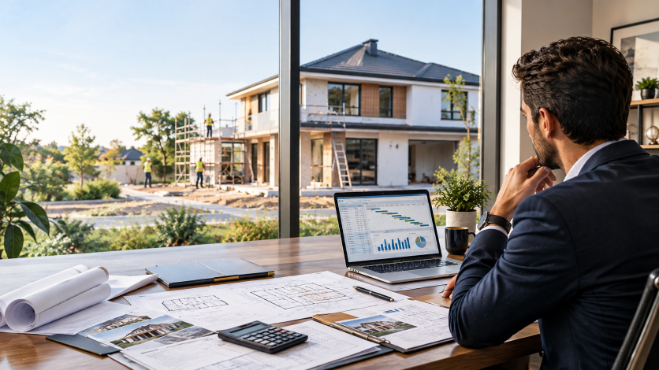
Short-term real estate projects can be an attractive option for property investors who want to complete a project, sell or refinance the property, and move on to their next investment within a relatively short period. Unlike traditional real estate investing, where investors may hold a property for many years and earn rental income, short-term projects usually focus on creating value within a defined timeline.
These projects can include buying a property that needs repairs, renovating an older house, improving a small commercial building, or purchasing land for a specific development. The main goal is to complete the planned work, increase the property's value, and choose the right exit strategy.
However, short-term real estate investing is not simply about buying a property cheaply and selling it for more money. Investors must understand how funding works, how long each stage may take, what costs they need to cover, and how they plan to recover their investment.
In this guide, we will explain short-term real estate projects in simple terms, including common funding methods, project timelines, budgeting, risks, and exit strategies. By understanding these basics, investors can make more informed decisions before starting a project.
Short-term real estate projects are property investments designed to reach a specific goal within a relatively short period. Depending on the property, location, financing arrangements, and amount of work required, a project might take several months or longer than a year.
The definition of short-term can vary between investors. For some, it means completing a renovation and resale within three to six months. For others, it may mean purchasing, improving, and selling a property over nine to eighteen months.
The important factor is that the investor begins with a clear plan for creating value and completing the investment.
For example, an investor might purchase an older house that needs repairs. After buying the property, the investor updates the kitchen, repairs damaged areas, improves the bathroom, and makes the home more appealing to potential buyers. Once the work is complete, the investor lists the house for sale.
If the final selling price is higher than the total investment and expenses, the project may generate a profit.
Common types of short-term real estate projects include:
Fix-and-flip projects: Buying properties that need repairs, improving them, and selling them.
Cosmetic renovations: Updating paint, flooring, lighting, kitchens, or bathrooms to improve a property's appeal.
Small property developments: Improving land or constructing a small property for sale.
Commercial property improvements: Updating an office, retail unit, or other commercial space before selling or leasing it.
Buy-improve-refinance projects: Purchasing a property, increasing its value, and refinancing it when the investor qualifies for suitable financing.
Each project has different costs, risks, and time requirements. The right approach depends on the investor's budget, experience, local market conditions, and investment goals.
Funding is one of the most important parts of a short-term real estate project. Investors need money to purchase the property, pay contractors, buy materials, cover professional fees, and manage expenses until the project is completed.
Some investors use their own savings, while others work with lenders or private investors. The best funding method depends on how much money is required, how quickly the project must begin, and how the investor plans to repay the funds.
Some investors use their own money to purchase and improve a property. This approach can provide greater control because the investor does not have to make loan payments or meet a lender's repayment schedule.
Using personal funds may also reduce interest expenses and financing fees.
However, it has its own risks. A property project can require more money than expected, particularly when repairs uncover hidden problems. Investing too much personal capital in one property can also leave the investor with limited funds for emergencies or other opportunities.
Before using savings, investors should calculate the full project budget and keep a separate reserve for unexpected costs.
Short-term property loans are designed to provide financing for a limited period. They may be used by investors who need funds to purchase or renovate a property before selling it or arranging longer-term financing.
Depending on the lender and the loan agreement, these loans may offer faster decisions than some traditional financing options. However, approval speed and requirements vary.
Investors should carefully review the interest rate, arrangement fees, repayment schedule, collateral requirements, and any early repayment charges.
A short-term loan can become expensive if the project takes longer than planned. For this reason, investors should not assume that a property will sell quickly or that refinancing will automatically be available.
Private money financing involves obtaining funds from an individual or private investment group. The investor may agree to provide money in return for interest payments, a share of the project's profit, or another arrangement agreed upon by both parties.
For example, a property investor may have the experience to renovate a house but may not have enough money to purchase it. A private investor could provide the required capital under a written agreement.
Before accepting private funding, both parties should clearly understand their responsibilities, expected returns, repayment conditions, and what happens if the project loses money or takes longer than expected.
Written contracts and appropriate legal advice can help reduce misunderstandings.
A joint venture allows two or more parties to work together on a real estate project. One partner might contribute money, while another manages the property search, renovation, contractors, and sale.
This arrangement can help investors combine different skills and resources.
However, partnerships need clear rules. The agreement should explain who makes decisions, how expenses are approved, how profits or losses are divided, and how disagreements will be handled.
Investors should never rely only on verbal promises when significant amounts of money are involved.
Seller financing is an arrangement in which the property seller provides financing to the buyer instead of requiring the buyer to obtain all the purchase funds from a traditional lender.
The buyer and seller agree on the payment structure, interest rate if applicable, repayment period, and other conditions.
This option may be useful in some transactions, but it depends on the seller's willingness, local law, the property's circumstances, and the terms of the agreement. Buyers should have the arrangement reviewed by a qualified professional before proceeding.
A realistic timeline helps investors manage money, contractors, and expectations. Even a relatively small renovation can involve several stages, and delays in one stage can affect everything that follows.
The following is an illustrative timeline for a straightforward property renovation and resale. Actual project durations can vary significantly.
Estimated period: 2–6 weeks
The first step is to find a property that fits the investment plan. Investors should study local property prices, buyer demand, comparable sales, repair requirements, and the likely selling price after improvements.
They should also check the property's legal status, ownership records, taxes, outstanding charges, and any restrictions that may affect renovation or resale.
A property that looks inexpensive may still be a poor investment if it requires major structural work or is located in an area with weak buyer demand.
Estimated period: 2–8 weeks
After selecting a property, the investor arranges financing, negotiates the purchase, completes due diligence, and works toward closing the transaction.
The timeline depends on the financing method, title checks, inspections, documentation, and the seller's circumstances.
Investors should avoid committing to a project until they understand how the purchase will be funded and what conditions must be met before the transaction can close.
Estimated period: 4–16 weeks or longer
Once the purchase is complete, the investor begins the planned improvements. These may include painting, replacing flooring, updating fixtures, repairing plumbing, improving landscaping, or renovating rooms.
The length of this stage depends on the size and condition of the property, contractor availability, material delivery, and any permits or inspections required.
A detailed work schedule can help prevent unnecessary delays. Investors should also inspect completed work regularly rather than waiting until the end of the project to identify problems.
Estimated period: 1–4 weeks
After renovation, the investor prepares the property for the market. This can include cleaning, staging, photography, arranging valuations, setting an asking price, and selecting an estate agent or other sales professional.
A property should be presented honestly and in accordance with applicable disclosure requirements.
Pricing is particularly important. An asking price that is too high may discourage buyers, while an unnecessarily low price can reduce the amount the investor recovers.
Estimated period: 2–12 weeks or longer
The final stage involves finding a buyer, negotiating an offer, completing inspections, resolving any required conditions, and finalizing the sale.
The property may sell quickly, or it may remain on the market for months. Local demand, mortgage availability, seasonality, property condition, and pricing can all influence the result.
Investors should budget for holding costs throughout this period rather than assuming the renovation will be followed by an immediate sale.
A common mistake in short-term real estate investing is calculating profit using only the purchase price and expected selling price.
A realistic budget must include every major expense connected with the project.
Typical costs include:
Property purchase price
Legal fees and closing costs
Inspection and valuation fees
Renovation materials and contractor payments
Permits and professional services
Loan interest and financing fees
Property taxes and insurance
Utilities and maintenance
Marketing and estate agent fees
Selling and closing expenses
A reserve for unexpected repairs
Investors should also account for any applicable taxes on profits according to their local rules.
Imagine an investor purchases an older property for $150,000. The investor plans to renovate it and sell it after the work is complete.
The estimated budget might look like this:
| Expense | Estimated cost |
|---|---|
| Property purchase | $150,000 |
| Renovation work | $25,000 |
| Legal and closing costs | $4,000 |
| Financing and holding costs | $6,000 |
| Marketing and selling costs | $10,000 |
| Contingency reserve used | $5,000 |
| Total project cost | $200,000 |
If the property sells for $225,000, the estimated amount remaining after these listed costs is $25,000.
This is an illustrative calculation, not a prediction of actual investment performance. It assumes that the listed costs include the relevant expenses and does not account for any additional tax liabilities that may apply.
The final result could be lower if the sale price falls, the renovation costs more than expected, or the property takes longer to sell.
The example shows why investors should estimate the full cost before purchasing a property.
An exit strategy is the plan an investor uses to complete an investment and determine how to recover the money invested in it.
In a short-term project, the exit strategy should be considered before purchasing the property. It helps the investor decide which property to buy, how much to spend on improvements, what financing to use, and how much time to allow for the project.
Several exit strategies are available, but not every option is suitable for every property.
Selling a renovated property is one of the most common exit strategies for short-term investors.
The investor purchases a property, completes the planned improvements, and sells it to another buyer. The goal is to sell for enough to cover the purchase price, renovation expenses, financing costs, selling expenses, and other applicable costs.
This strategy works best when there is sufficient buyer demand and the expected sale price is supported by comparable properties in the same area.
However, investors cannot control exactly when a buyer will make an acceptable offer. They should consider what they will do if the property takes longer to sell than expected.
Refinancing involves replacing an existing loan with a new loan under different terms. Depending on the lender, property value, investor qualifications, and local lending rules, refinancing may allow an investor to move from short-term financing to a longer-term arrangement.
Some investors improve a property's condition or income potential before seeking refinancing.
For example, an investor may renovate a small rental property and then apply for a longer-term mortgage. If approved, the investor may retain ownership instead of selling immediately.
However, refinancing is not guaranteed. Lenders may require a valuation, proof of income, a minimum ownership period, or other conditions. The investor should not rely on refinancing without understanding the relevant requirements.
If the property is suitable for tenants, renting it may provide an alternative to selling.
An investor might decide that the rental income and potential long-term appreciation make holding the property more attractive than accepting the available sale offers.
Before choosing this strategy, the investor should estimate achievable rent, vacancy periods, maintenance, insurance, management costs, taxes, and ongoing financing payments.
Rental income is not the same as profit. A property that produces monthly rent may still generate negative cash flow if its expenses are too high.
Investors should also confirm that the property meets applicable rental standards and legal requirements.
Another possible exit strategy is selling the property to an investor who wants to complete additional improvements, rent it out, or hold it for future appreciation.
This can be useful when a property is suitable for investment but does not appeal to typical homebuyers in its current condition.
The selling price will depend on the property's condition, expected income, location, repair needs, and the buyer's financial calculations.
Investors should compare the actual offers available with their original budget instead of assuming another investor will pay the desired price.
Funding, timelines, and exit strategies are closely connected. A decision about one can affect the other two.
For example, an investor who uses an expensive short-term loan needs to understand how long the loan can remain outstanding and what happens if the property does not sell before repayment is due.
If renovation work takes longer than expected, interest and holding costs may increase. A delayed sale can reduce the project's profit or create a cash-flow problem.
On the other hand, an investor using personal funds may have more flexibility about when to sell, although their money remains tied up in the property.
A rental exit strategy also changes the financial calculations. Instead of focusing only on the resale price, the investor needs to consider rental income, operating expenses, vacancy, and the cost of any long-term financing.
Before starting a project, investors should answer three important questions:
How will the project be funded? Identify the source of money, financing costs, repayment conditions, and available reserves.
How long will the project take? Estimate the time required for purchase, renovation, marketing, and closing, with room for delays.
How will the investment end? Decide whether the preferred exit is a sale, refinancing, rental ownership, or another realistic option.
The answers should fit together in one practical investment plan.
Short-term property investments can face several challenges. Planning ahead can help investors identify problems before they become expensive.
Older properties may contain hidden problems such as water damage, outdated electrical systems, structural defects, or plumbing issues.
Investors should arrange appropriate inspections and obtain realistic contractor estimates. A contingency reserve can help cover unexpected work.
A property may take longer to sell because of weak demand, competition, pricing, or changing market conditions.
Investors should estimate holding costs for a longer period and consider how they would respond if the expected buyer does not appear.
A loan with high fees or a short repayment deadline can create financial pressure.
Investors should compare the total cost of different financing options, review the terms carefully, and seek professional advice when needed.
Not every renovation increases a property's market value by the amount spent.
Investors should focus on improvements that make sense for the local market and the likely buyer. Expensive personal design choices may not produce a matching increase in resale value.
A planned sale may become difficult if market conditions change.
Investors should consider alternatives before purchasing the property, such as whether renting or refinancing could be feasible. These options should be supported by realistic numbers and confirmed financing requirements, not assumptions.
No property investment is completely risk-free, but careful preparation can improve decision-making.
Start by researching the local market and comparing the property with similar homes or buildings that have recently sold. Use conservative estimates for the resale price and include all expected expenses in the budget.
Next, obtain appropriate inspections and verify important legal details before completing the purchase. If renovation work is required, use qualified professionals where necessary and establish a clear schedule.
Investors should maintain records of payments, invoices, contracts, and changes to the original plan. Reviewing actual spending against the budget can help identify problems early.
It is also important to protect against delays. Keep sufficient funds available for ongoing expenses and avoid relying on the most optimistic timeline.
Finally, understand the financing agreement and the exit strategy. If the project depends on selling the property by a certain date, the investor should consider what will happen if the sale is delayed or the final offer is lower than expected.
For complex projects, qualified real estate, legal, tax, and financial professionals can help investors assess the relevant risks.
Short-term real estate investing can appeal to beginners, but it requires research, planning, and careful money management.
A beginner may benefit from starting with a smaller project that has manageable repair requirements and a clear resale market. Cosmetic improvements can be easier to plan than major structural renovations, although every property requires proper inspection.
New investors should also understand that a project can lose money. Unexpected repairs, interest expenses, delays, and lower-than-expected sale prices can affect the final result.
Before committing funds, beginners should create a complete budget, compare financing options, study local property prices, and identify a realistic exit strategy.
It may also help to work with experienced contractors or property professionals who understand the local market.
The goal should not simply be to complete a project quickly. It should be to make a well-informed investment decision based on realistic costs, timelines, and potential outcomes.
Short-term real estate projects can offer investors a way to create property value within a defined period. However, success depends on more than finding an inexpensive property or completing renovations.
Investors need to understand how funding works, estimate a realistic timeline, calculate the total project cost, and choose an exit strategy that fits their financial goals.
Personal savings, short-term loans, private financing, partnerships, and seller financing may provide different ways to fund a project. Each option comes with its own conditions and risks.
Similarly, selling a renovated property, refinancing, or renting it can lead to different financial outcomes. The right choice depends on the property, market demand, available financing, and the investor's ability to manage ongoing expenses.
The most useful step is to plan the entire project before purchasing the property. When the funding, timeline, budget, and exit strategy work together, investors can make better decisions and prepare for unexpected challenges.
Real estate investing always involves uncertainty, and profits are never guaranteed. Careful research, realistic calculations, and professional guidance can help investors understand the risks and approach short-term property projects with greater confidence.
A few years ago, I had four monitors set up on my desk, constantly flashing red and green. I was...
• 8 minutes read
Years ago, I used to think the stock market was a playground reserved exclusively for guys in tailored suits who...
• 6 minutes read
Value-Add Real Estate Investing: How Property Improvements Create Potential Returns Real estate investing is not always about buying a property...
• 16 minutes read